Switching Careers to Insurance Sales: What You Need to Know
Licensing takes weeks, not years, but commission-weighted pay means the first six months are usually the hardest part of the move.
Quick answer
- Licensing runs two to eight weeks; most people reach steady commission income somewhere between months 9 and 18, making a realistic total transition 12-24 months.
- Licensing exams run 50-200 items in two to three hours, with a passing score of at least 70% in most states and an overall pass rate around 60% (Insurance Business magazine citing NAIC, 2024).
- Budget for pre-licensing courses, per-line state fees, and a 3-6 month income gap — independent agents may be commission-only (U.S. Bureau of Labor Statistics, 2025).
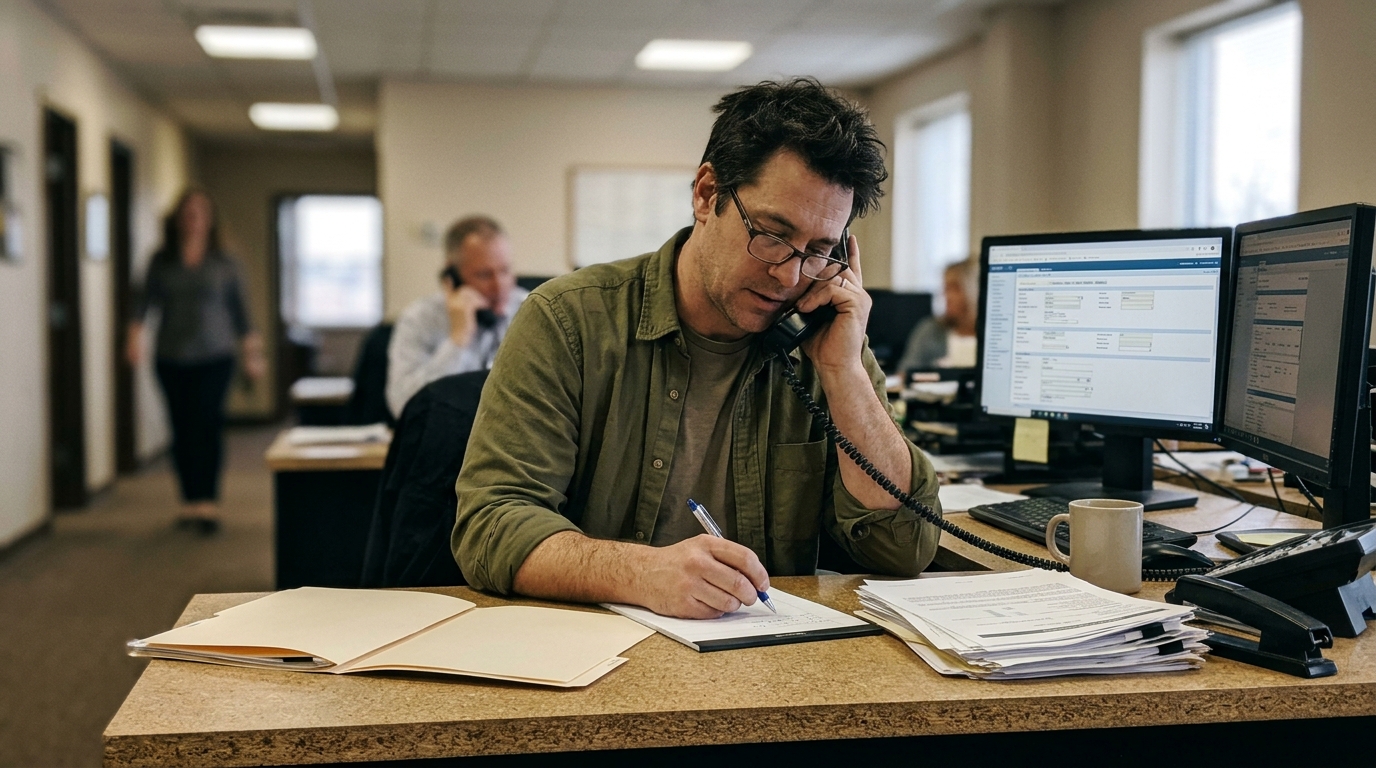
Insurance sales is one of the more open mid-career switches available: the U.S. Bureau of Labor Statistics (2025) reports that typical entry-level education is a high school diploma or equivalent, with no related work experience required and moderate-term on-the-job training. What you do need is a state license, and getting one — pre-licensing coursework plus the state exam — can take two to eight weeks depending on your pace (Insurance Business magazine, 2024).
The real hurdle is money, not entry. Commissions are the most common form of pay, especially for experienced agents (U.S. Bureau of Labor Statistics, 2025), so plan for a thin first few months while you build a book of business.
What the Work Actually Involves
Most agents work in an office, though some travel to meet clients, and most work full time (U.S. Bureau of Labor Statistics, 2025). A typical weekday for a newer agent looks something like this:
- 2-3 hours of outbound contact. Calls, texts and emails to leads, referrals and past quotes that went cold. O*NET lists seeking out new clients through networking as a core task, and in your first year it is the task that determines your income.
- 2-3 hours of quoting and policy comparison. You take a client's details, run them through carrier rating systems, and build options. O*NET describes this as customizing insurance programs to suit individual customers and explaining the features, advantages and disadvantages of each policy.
- 1-2 hours of service and administration. Renewals, endorsements, certificates of insurance, claims hand-offs, and keeping records current. O*NET lists these administrative duties as part of the job, and they grow as your client base grows.
- 30-60 minutes of follow-up discipline. Logging activity in the agency's CRM, scheduling callbacks, and chasing signatures on applications.
Over a week, expect a few evening or early-morning appointments if you sell life and health, because that is when working families are available. Expect rejection too — the Bureau of Labor Statistics (2025) lists self-confidence, including the ability to maintain composure after rejection, as an important quality for the role, alongside analytical, communication, interpersonal skills and initiative.
The mix shifts with your setup. Captive agents at a carrier office spend more time on company-provided leads and compliance; independent agents spend more time on marketing and carrier relationships. About 63% of agents work for insurance agencies and brokerages and 12% are self-employed (U.S. Bureau of Labor Statistics, 2025).
Who This Career Change Suits
- Retail or restaurant managers. You already handle walk-in objections, upsells and daily numbers. Quoting a policy is a structured version of the same conversation, and you are used to being measured weekly.
- Licensed real estate agents. You have lived on commission, managed a pipeline, and passed a state licensing exam before. The income pattern of insurance will not shock you.
- Bank tellers and personal bankers. You understand regulated products, disclosure language and KYC-style verification. Moving to life and health or to Series 6 products is a short conceptual step.
- Elementary and secondary teachers. Explaining the features, advantages and disadvantages of a policy to a nervous buyer is explanation under pressure, which is what you have done for years.
- Medical billers, pharmacy techs and front-desk clinic staff. Health insurance sales rewards people who already know deductibles, networks and formularies, because clients ask about them constantly.
- Military veterans transitioning out. Structured training, compliance rules and continuing-education requirements are familiar, and many agencies hire on discipline rather than degree.
- Former auto body estimators, contractors or claims adjusters. Property and casualty quoting depends on understanding what a repair or rebuild actually costs.
- People who need composure after a no. If a lost sale ruins your week, this is a hard fit. If it is just Tuesday, it is a strong one.
Transferable Skills That Carry Over
| Prior Career | Skill | How It Applies Here |
|---|---|---|
| Retail store manager | Handling objections at the point of sale | Converting a price-shopping caller into a bound policy without discounting value |
| Elementary teacher | Explaining complex material simply | Walking a client through deductibles, riders and exclusions so they actually understand what they bought |
| Personal banker | Working inside a regulated product set | Staying within state insurance law and disclosure rules; a natural path toward the FINRA Series 6 for mutual funds and variable annuities |
| Medical biller or pharmacy tech | Reading coverage and benefit rules | Comparing health plan networks, copays and out-of-pocket maximums for clients |
| Auto body estimator or contractor | Estimating replacement cost | Setting accurate dwelling and vehicle coverage limits in property and casualty quoting |
| Restaurant server or bartender | Fast rapport with strangers | Networking for new clients, which O*NET lists as a core task of the job |
| Call center or collections agent | High-volume phone work and call discipline | The 2-3 hours of daily outbound contact that drive a new agent's first-year commissions |
How to Get Started
- Pick your line of authority first. Separate licenses are required for life and health versus property and casualty (U.S. Bureau of Labor Statistics, 2025). Choose one to start — a second line means a second exam and a separate fee in most states (Insurance Business magazine, 2024).
- Check your state's eligibility rules. Most states require applicants to be at least 18, have no fraud or felony charges, owe no outstanding federal or state income taxes, and pass a background check (Insurance Business magazine, 2024). Rules differ by state, so read your own department of insurance website before paying for anything.
- Complete state-approved pre-licensing coursework. Most states require specified courses covering insurance fundamentals and state insurance law before you can sit the exam (U.S. Bureau of Labor Statistics, 2025). Your state department of insurance publishes the approved provider list.
- Sit the state exam. Expect 50 to 200 items in two to three hours, with a passing score of at least 70% in most states; results are valid for two years (Insurance Business magazine, 2024). If you already hold a CLU designation you may only need the Life & Health Laws and Regulations exam; a CPCU holder may only need the Property & Casualty Laws and Regulations exam (Insurance Business magazine, 2024).
- Apply for the license and pay the state fee. Fees vary by state and are charged per line of authority (Insurance Business magazine, 2024).
- Interview at both captive and independent shops. Ask directly how you would be paid: salary only, salary plus commission, salary plus bonus, or commission only (U.S. Bureau of Labor Statistics, 2025). Ask how leads are supplied and what the first-year retention of new agents looks like.
- Take the on-the-job training seriously. Moderate-term on-the-job training is typical for the occupation (U.S. Bureau of Labor Statistics, 2025). Use it to learn carrier appetite — which company wants which risk — because that knowledge is what makes quoting fast.
- Plan your second credential. Once producing, consider the FINRA Series 6 or Series 7 if you want to sell securities-based products (U.S. Bureau of Labor Statistics, 2025), or an industry designation. Designations are not required for employment but may give candidates an advantage (U.S. Bureau of Labor Statistics, 2025).
Costs and Time Commitment
Figures below are planning ranges, not quotes. Pre-licensing course prices and state fees differ by state and provider, so confirm current amounts with your state department of insurance.
| Item | Typical Cost | Typical Time |
|---|---|---|
| Pre-licensing coursework (life & health or property & casualty) | A few hundred dollars per line in most states; confirm with approved providers | Part of the two-to-eight-week licensing window (Insurance Business magazine, 2024) |
| State licensing exam and application fee | Varies by state, charged separately for each line of authority (Insurance Business magazine, 2024) | Exam sitting of two to three hours (Insurance Business magazine, 2024) |
| Retake after a failed attempt | Repeat exam fee plus study time | Add 2-4 weeks; the overall pass rate is around 60% (Insurance Business magazine citing NAIC, 2024) |
| Income gap while building a book | Plan for 3-6 months of living expenses in savings | Months 1-6; commission-only roles pay nothing until policies bind (U.S. Bureau of Labor Statistics, 2025) |
| Continuing education | Course fees each renewal cycle | 24 hours per two-year license term, including 3 hours of ethics (Insurance Business magazine, 2024) |
| Optional FINRA Series 6 or Series 7 | Exam and sponsorship costs through your firm | Usually attempted after your first year on the job |
A realistic total transition is 12 to 24 months: two to eight weeks to license, then roughly 9 to 18 months before renewals and referrals make your income predictable. The concrete tradeoff is the gap. If you leave a salaried job for a commission-only independent role, you are funding 3-6 months of expenses yourself.
Frequently asked questions
Am I too old to start in insurance sales at 50 or 55?
Age-related worry in this field usually shows up in the 45-60 range, where candidates assume agencies want 25-year-olds. The occupation's entry requirements work against that: the U.S. Bureau of Labor Statistics (2025) reports a high school diploma or equivalent as typical entry-level education with no related work experience required, and most states set only a minimum age of 18 (Insurance Business magazine, 2024). Agencies hiring commission-weighted producers care about whether you can build a pipeline, and a 25-year local network is a selling point, not a liability.
How much do insurance sales agents actually earn?
The median annual wage was $62,280 in May 2025, or $29.94 per hour (U.S. Bureau of Labor Statistics, 2025). The spread is wide: the lowest 10 percent earned less than $37,330 and the highest 10 percent more than $138,140 in the same period (U.S. Bureau of Labor Statistics, 2025). Where you land depends heavily on whether you are paid salary, salary plus commission, or commission only, so check current figures on the BLS Occupational Outlook Handbook page before you budget.
Is the job market stable enough to switch into?
Employment of insurance sales agents is projected to grow 3 percent from 2025 to 2035, about as fast as the average for all occupations, with roughly 43,100 openings projected each year on average over the decade (U.S. Bureau of Labor Statistics, 2025). Agents held about 572,600 jobs in 2025 (U.S. Bureau of Labor Statistics, 2025). Most of those annual openings come from replacement needs rather than new positions, which is why entry-level hiring stays steady.
Do I need a college degree?
Not as a licensing requirement — the U.S. Bureau of Labor Statistics (2025) lists a high school diploma or equivalent as typical entry-level education. O*NET does classify the role in Job Zone Four, 'Considerable Preparation Needed,' with an SVP range of 7.0 to less than 8.0, meaning most occupations at that level require a bachelor's degree but some do not. In practice, individual employers set their own bar, so a degree may matter at a large carrier and not at a local independent agency.
What if I fail the state exam?
It happens often enough that you should plan for it: the overall passing rate is around 60%, varying by line of authority (Insurance Business magazine citing NAIC, 2024). Most states set the passing score at 70% on an exam of 50 to 200 items (Insurance Business magazine, 2024). Rebook, re-study the state law section, and add two to four weeks to your timeline rather than abandoning the plan.
Sources
- U.S. Bureau of Labor Statistics — Insurance Sales Agents : Occupational Outlook Handbook (2025)
- O*NET OnLine (U.S. Department of Labor) — 41-3021.00 - Insurance Sales Agents
Written by
Priya tracks wages, layoffs, and the slow shifts in what counts as a stable job. She writes for readers trying to make sense of numbers that rarely match their own experience.